
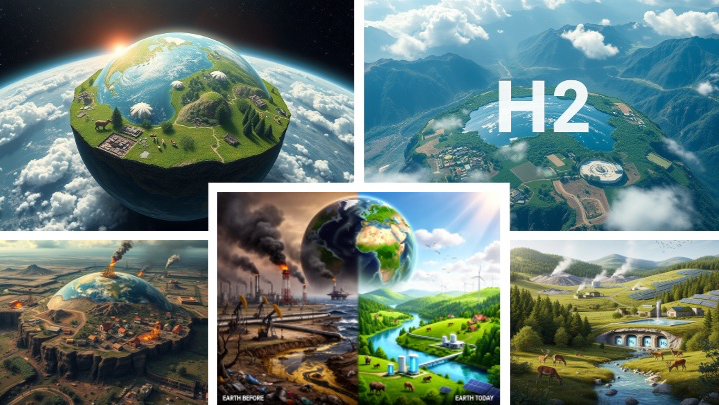
Oil demand plateau and end-of-cycle dynamics: anatomy of a geopolitical realignment
Foreword
By the early 2030s, the progressive erosion of oil’s centrality is emerging as a defining driver of global energy, economic, and geopolitical realignment.
Recent developments within major oil companies constitute an early signal of this shift -one that remains insufficiently integrated into prevailing strategic and financial assessments.
Managerial instability across the industry reflects a broader pattern of converging indicators: shortened investment horizons, accelerated capital redistribution, gradual erosion of human capital, semantic shifts in strategic positioning, rising regulatory and litigation exposure, and a widening gap between stated commitments and actual capital allocation.
Taken together, these signals suggest not a controlled transition, but a defensive end-of-cycle phase. This dynamic is further amplified by the emergence of potentially abundant decarbonized energy resources -such as natural hydrogen (or white H2) and, in the nearer term, compact nuclear fusion -whose prospective diffusion and governance frameworks are beginning to take shape.
These developments also shed light on current geopolitical tensions. Beyond cyclical rivalries, what is unfolding is the gradual erosion of an international order historically structured around the control and securitization of hydrocarbon flows. The credible prospect of a structural plateau in oil demand places rent-dependent economies under increasing pressure, encouraging accelerated reserve monetization strategies and the strategic instrumentalization of remaining energy interdependencies.
This inflection point represents more than an energy transition. It signals a reconfiguration of power regimes rooted in the industrial carbon order.
For investors, this shift warrants heightened scrutiny. The combination of structural demand plateauing, intensifying regulatory and environmental constraints, and the emergence of scalable low-carbon alternatives increases the likelihood of progressive fossil asset devaluation.
Capital allocation frameworks anchored in past cycles may prove insufficient. Strategic positioning must now incorporate the possibility of a durable realignment in global energy comparative advantages.
The strategic priority is progressively moving from resource expansion to the preservation of influence and fiscal capacity within a structurally constrained demand environment. Seen in this light, today’s geopolitical tensions appear less episodic than systemic indicative of competitive adjustments likely to deepen as the energy order evolves.
The post-oil era, now widely anticipated around 2030, is being decided today.
Most international projections now converge on a peak in global oil demand by around 2030, under current public-policy frameworks.
In its latest Energy Outlook, BP expects demand to crest at roughly 103.4 million barrels per day by 2030, followed by a marked decline toward mid-century.
The International Energy Agency (IEA), in Oil 2025: Analysis and Forecast[1] to 2030, anticipates a production surplus and a stabilization toward the end of the decade, around 105.5 million barrels per day, with regional variations depending on uses and sectors.
These inflection points are occurring without any significant strengthening of global climate policies, widening the gap between the current fossil-fuel trajectory and the objectives of the Paris Agreement- most notably the goal of limiting warming to 1.5°C.
This shift is not merely energy related. It is industrial, economic, and geopolitical.
The post-oil era has begun.
It is no longer a hypothetical exercise, but a transformation already embedded in investment decisions, industrial trade-offs, and strategies of sovereignty.
In this context, clinging to narratives that favor the status quo of the global energy mix amounts to underestimating a major systemic risk. Anticipation, investment, and decarbonization are becoming strategic imperatives.
Recent analyses by Rystad Energy[2], alongside those of other independent institutions, confirm a peak in global oil demand in the early 2030s, followed by a rapid decline in scenarios compatible with international climate goals. Even the most conservative assumptions now point to structurally limited demand growth.
The signal is clear: the global energy system is changing course -faster than expected.
The question is no longer whether the transition will occur, but at what pace and under what conditions.
This shift creates a structural necessity: accelerating the deployment of decarbonized resources capable of meeting large-scale, continuous, and sovereign energy needs.
Oil majors: governing uncertainty
Less than two years after appointing its discreet chief financial officer, Murray Auchincloss, as chief executive, BP[3] has once again changed leadership, promoting the American executive Meg O’Neill[4].
A former head of Woodside Energy, she becomes both the first outsider to be appointed to the role and the first woman to lead one of the world’s major international oil companies.
Unusual in a sector historically defined by managerial continuity, the decision reflects BP’s need to arbitrate between competing pressures: meeting financial-market expectations, rebalancing its portfolio between fossil-fuel activities with limited growth prospects beyond 2030 and rapidly expanding low-carbon businesses, and navigating an international environment marked by an ongoing but still unstable energy transition.
While BP’s case is particularly striking, it fits within a broader pattern affecting most oil majors. Without experiencing the same frequency of leadership turnover, several players -Shell, Chevron[5], and TotalEnergies[6] among them- have undertaken governance reorganizations, reshuffled executive committees, and introduced sometimes significant strategic adjustments in recent years.
This trend highlights a growing tension between the stability traditionally prized in this capital-intensive sector and the need to adapt strategic orientations more rapidly in an energy landscape that has become more uncertain, more politicized, and more volatile.
Governance is increasingly emerging as a strategic lever in its own right, used to lend credibility to shifts in trajectory vis-à-vis investors, regulators, and markets. It has become a mirror of an energy transition that remains only partially mastered and lacking a stabilized path.
Hydrogen: a strategic lever of the transition
In this context, hydrogen (H₂) takes on major strategic importance, including in liquid form (LH₂), whose industrial mastery has been established for decades.
The first commercial flight of a liquid-hydrogen-powered aircraft, as early as 1985 (the Tupolev TU-155[7] in the former Soviet Union), serves as a reminder that this technology is not a distant prospect but rests on a proven scientific and industrial foundation.
Natural hydrogen (often referred to as “white” or native hydrogen) is thus emerging as a strategic complement to nuclear fission[8] technologies and, in the medium term, to compact nuclear fusion[9].
Present across the planet in considerable volumes, as little as 2% of identified global natural-hydrogen resources could, according to some estimates (US Geological Survey, 2025, Link[10]), cover some 200 years of global energy demand.
Early techno-economic assessments further suggest that natural hydrogen may rank among the most competitive forms of hydrogen[11], with production costs potentially far lower than those of electrolytic hydrogen, depending on geological settings and operating conditions.
In certain cases, these costs could approach -or even undercut- those of green hydrogen, which remains dependent on the availability and price of renewable electricity[12].
As a local, decarbonized resource, natural hydrogen thus opens new perspectives for energy sovereignty, industrial resilience, and the diversification of value chains.

In this context, accelerating the exploration and development of natural hydrogen is no longer a marginal option but a credible and structuring lever of the energy transition.

Preventing disorder in the post-oil era
The global peak in hydrocarbon demand (oil and gas) does not signal the immediate end of oil, but rather the entry into a phase of profound reconfiguration of an international order that has, for nearly two centuries, been structured around the centrality of fossil rents.
As this rent erodes, the main challenge lies less in physical access to resources than in the geostrategic adjustments imposed by the transition -particularly for states whose economic, fiscal, and social stability remains closely tied to oil and gas revenues.
For these countries, the energy transition represents a complex adaptation exercise, combining budgetary constraints, social pressures, and a redefinition of their international role.
History[13] shows that such deep transformations, when poorly anticipated, tend to generate prolonged periods of instability. In a highly interconnected global environment, marked by intensifying rivalries and multiple tensions, these dynamics can fuel potentially durable strategic volatility: regional realignments, indirect pressures, and heightened efforts to secure national interests and critical supplies.
On the eve of the Second World War, it was not the immediate scarcity of resources that weakened the international order, but rather the inability -or unwillingness- of states to absorb in time a rapid redistribution of productive capacities and rents.
The current situation cannot be mechanically equated with that of the 1930s. Yet it displays a structural similarity: a growing mismatch between the evolution of the global productive system and geopolitical frameworks inherited from an energy order approaching obsolescence.
The greatest risk and cost do not lie in the transition itself, but in the failure to anticipate it.
Toward an economy of abundant critical capacities
The end of oil’s centrality compels policymakers and investors alike to manage a transition with potentially destabilizing effects. The challenge is no longer merely to control the decline of an old model, but to prevent this historic shift from resulting in a lasting fragmentation of international balances.
This period also opens a major strategic opportunity: the transition toward an economy of abundant critical capacities.
The convergence of technologies -advanced artificial intelligence, small modular reactors (SMRs), compact nuclear fission and eventually fusion, hydrogen, regenerative agriculture, and predictive medicine- reduces constraints long regarded as structural: energy, food, information, and health.
Scarcity does not disappear; it changes in nature and geography.
For investors, the challenge is now clear: to identify the actors, technologies, and territories capable of turning this transition into a lever for sovereignty, resilience, and long-term stability.
Transitions do not reward the preservation of the past, but early investment in the order that is taking shape. Gingko confidential. Daniel Alystair. With my thanks to SH and GC. March 3rd, 2026. All rights reserved ©[1] AIE (2025): Oil 2025, Analysis and forecast 2030 (Link: https://www.iea.org/reports/oil-2025)
[2] Rystad Energy (2025) : https://www.rystadenergy.com et https://www.rystadenergy.com/insights/trump-and-energy-special-report-series
[5] A generational and strategic transition, marked since 2024–2025 by a deep reorganization of the operating structure, including leadership changes, streamlined governance, and a more explicit emphasis on capital discipline, against the backdrop of declining visibility on post-2030 fossil-fuel growth.
[6] A gradual strategic evolution at TotalEnergies, combining leadership continuity with accelerated diversification into electricity and LNG, alongside ongoing trade-offs between residual fossil-fuel growth and low-carbon investment. This hybrid trajectory reflects an effort to preserve multiple strategic options amid diminishing certainty over oil’s centrality beyond 2030.
[7] Capital (2022) : Tupolev TU-155, the 1st commercial plane flying with hydrogen : “… Developed from a Tupolev Tu-154, the Tupolev Tu-155 was indeed the first experimental aircraft to operate on liquid hydrogen. The tri-jet made its first test flight on April 15, 1988…”.
[8] Gingko Confidential (2025): To free energy, use hydrogen while awaiting nuclear fusion. Link : https://www.linkedin.com/pulse/gingko-confidential-free-energy-use-hydrogen-while-awaiting-valéry-dkjrf?utm_source=share&utm_medium=member_ios&utm_campaign=share_via
[9] Gingko International (2025): Compact nuclear fusion: Humanity’s ultima source of energy. Link : https://www.linkedin.com/pulse/gingko-confidential-nuclear-fusion-humanitys-ultimate-alves-valéry-qnbof?utm_source=share&utm_medium=member_ios&utm_campaign=share_via
[10] USGS (2025) : Link : https://www.linkedin.com/posts/alves-valéry-8bba2521_prospectivity-mapping-for-geologic-hydrogen-activity-7324066407137067008-jNv2?utm_source=share&utm_medium=member_ios&rcm=ACoAAASZ0M8BPMHu7GV1GCi-20rG-AsClpKNRQQ
[11] National Science Review, October 2025: Technico-economic viability of natural hydrogen. Natural hydrogen could be the most cost-effective hydrogen to produce, with costs shaped by geological conditions, ranging in some favorable scenarios from $0.18 to $1.50 per kg. Link : https://academic.oup.com/nsr/article/12/10/nwaf368/8246644.
[12] See foot page note 10, link to the article of National Science Review (October 2025: Techno-economic viability of natural hydrogen).
[13] The collapse of the Ottoman Empire in the early 20th century illustrates how a poorly anticipated energy and geopolitical transition can accelerate the redistribution of rents, the reorganization of alliances and borders, and lead to a prolonged period of regional instability.
Comments0
Please log in to see or add a comment
Suggested Articles